Articles | Updated 19 November 2026
Abbreviated tax invoice: what it is, what it must show, who can issue it
An abbreviated tax invoice is the short-form tax invoice a VAT-registered retailer gives walk-in customers. It needs no buyer name, address or tax ID, and it can show VAT-inclusive prices. The trade-off is that the buyer cannot claim the VAT on it as input tax. If a customer asks for a full tax invoice, the shop must issue one.
What an abbreviated tax invoice must show
Revenue Code section 86/6 and the Revenue Department's tax invoice handbook require at least 7 items on an abbreviated tax invoice
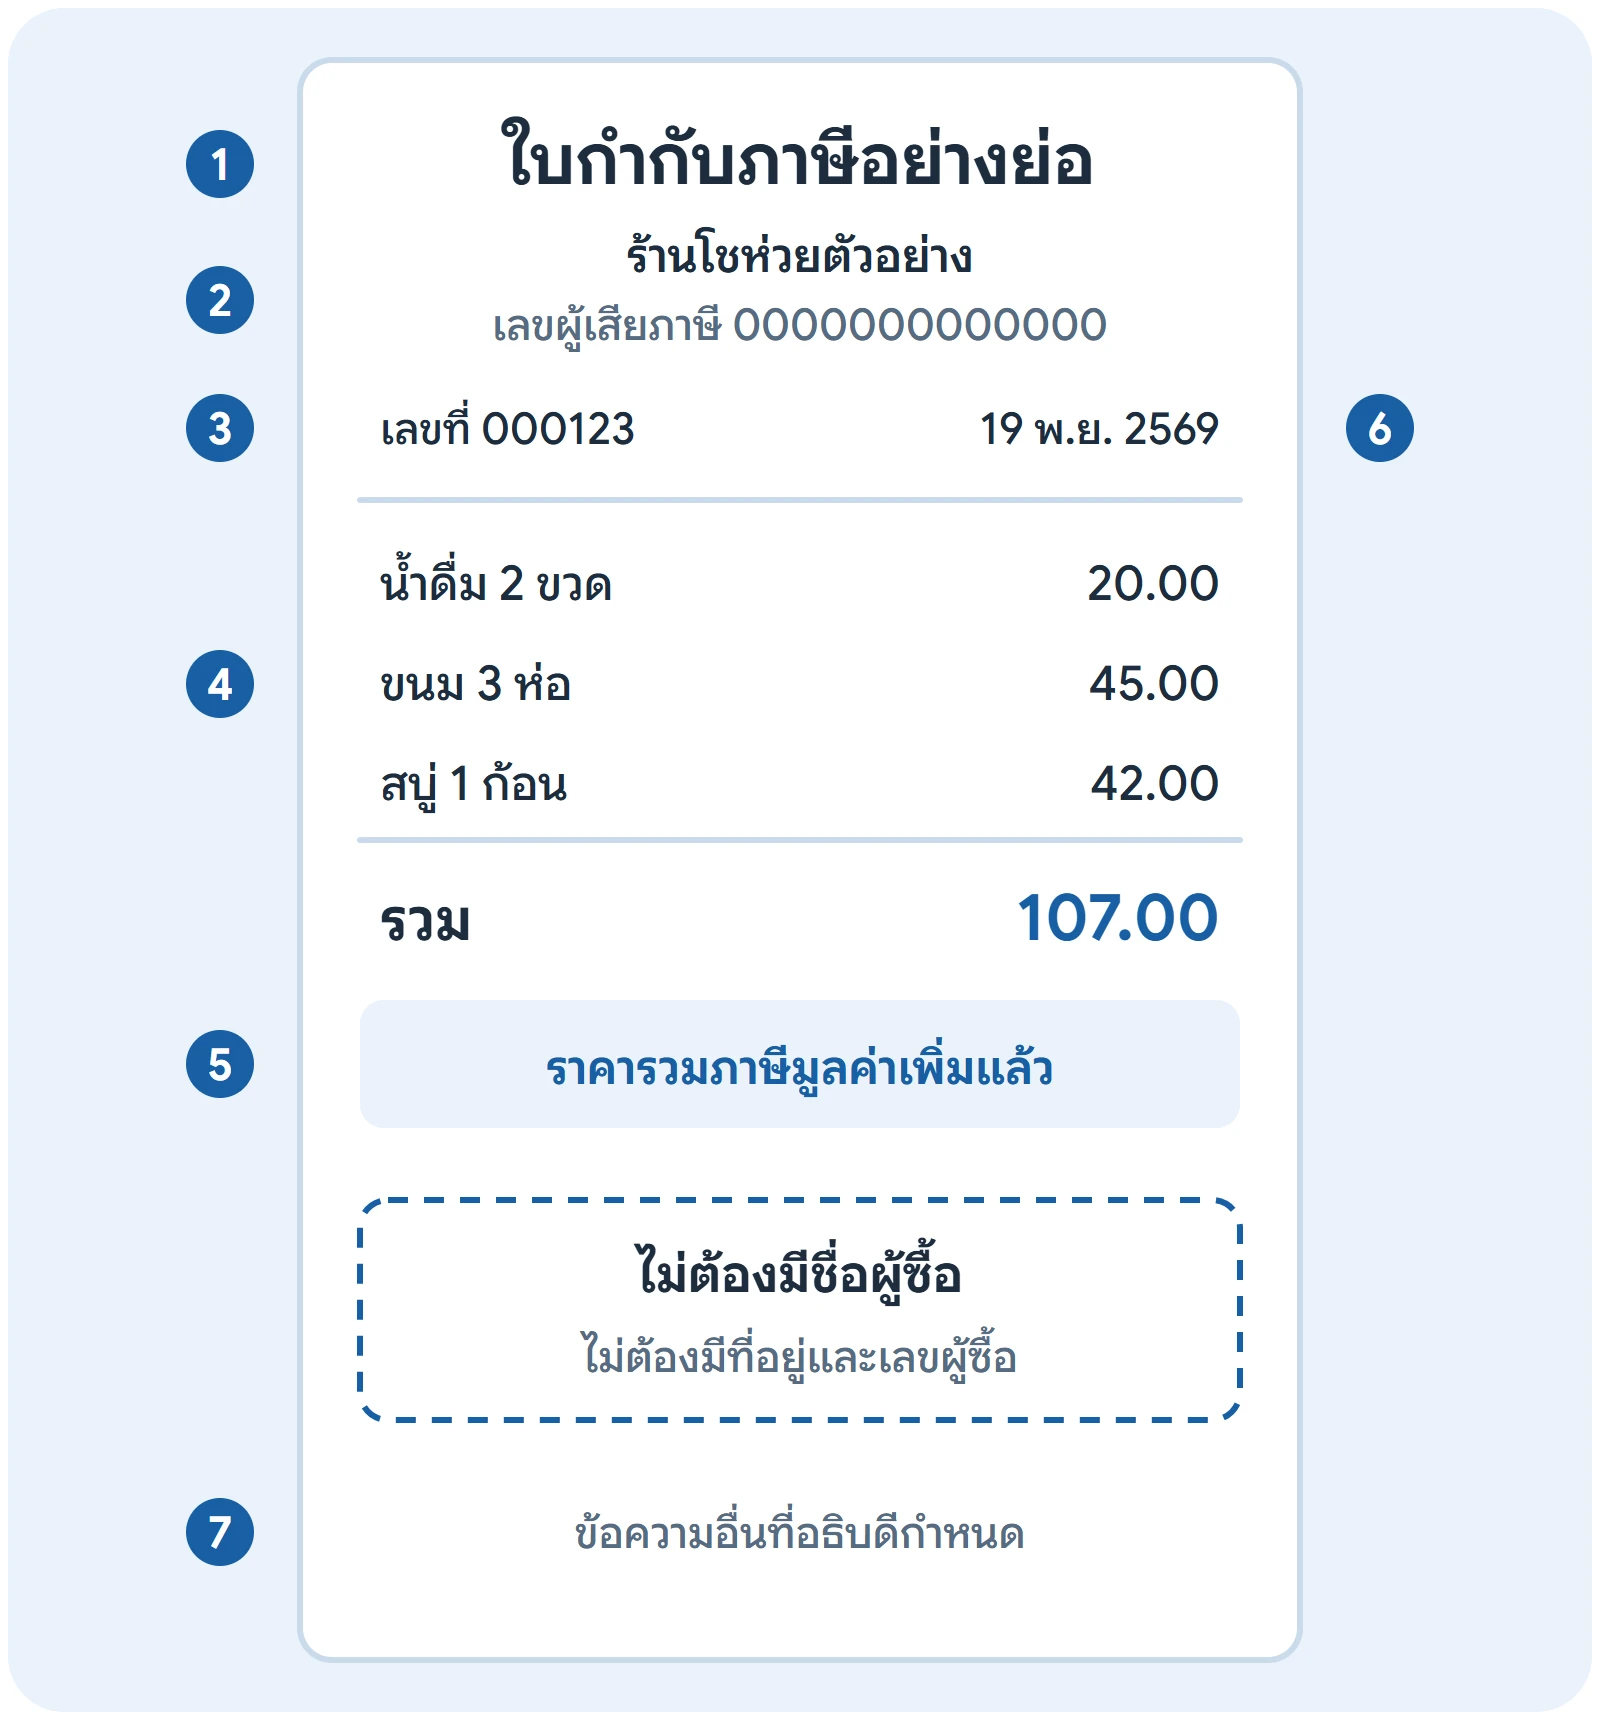
- The words 'abbreviated tax invoice', clearly visible
- The shop's name or short name and its 13-digit tax ID
- The invoice number, and the book number if any
- The name, kind, type, quantity and value of the goods or services
- The price, with a statement that it includes VAT
- The date of issue
- Other details set by the Director-General of the Revenue Department
How it differs from a full tax invoice
The Revenue Department's tax invoice handbook lists 3 differences
- No buyer name, address or tax ID is needed
- Product names may be codes, but the codes must be notified to the Revenue Department at least 15 days before use
- VAT can be included in the price without a separate line, but the invoice must say the price includes VAT
Who can issue one
VAT-registered shops that sell retail to consumers for their own use, such as grocery stores, pharmacies, petrol stations, department stores and stalls, or that provide small services to many people, such as repair shops, can issue abbreviated tax invoices without approval. An agent of the shop cannot issue them on its behalf.
A business that is not retail, such as a wholesaler selling to shops for resale, must first apply to the Director-General for approval under section 86/7 to issue abbreviated invoices. A shop not registered for VAT cannot issue any kind of tax invoice.
Example: a corner shop sale of 107 baht
A VAT-registered corner shop sells drinking water, snacks and soap to a walk-in customer for 107 baht in total
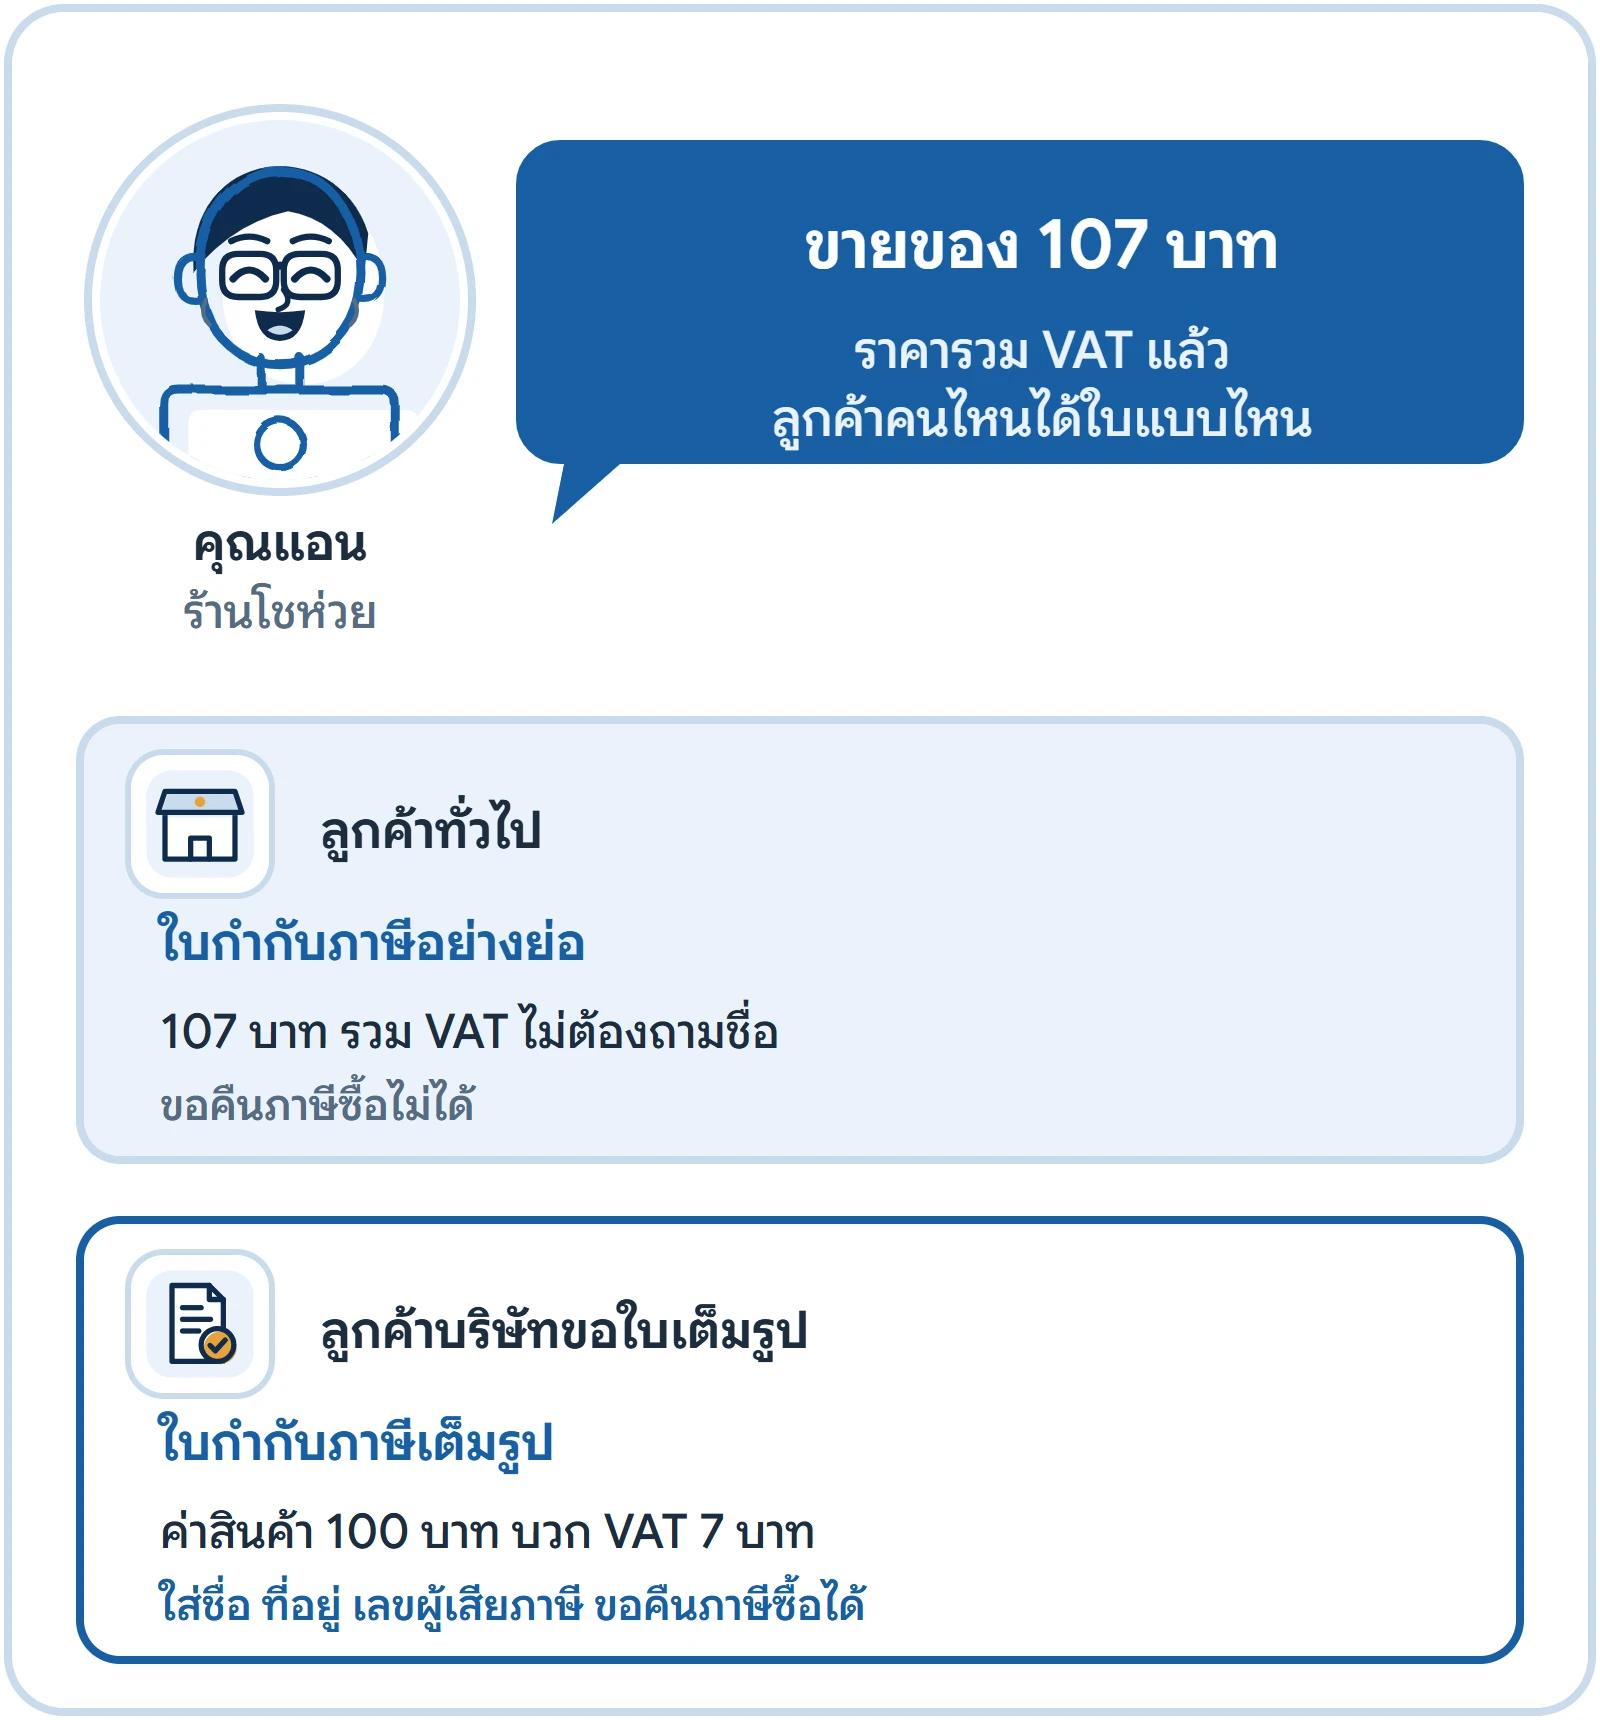
- For an ordinary customer, the shop issues an abbreviated tax invoice for 107 baht including VAT, without asking for a name
- The VAT in this amount is 107 x 7 / 107 = 7 baht; the shop includes these 7 baht as output tax in that month's PP.30
- If the customer is a VAT-registered company that wants to claim input tax, it must ask for a full invoice and the shop must issue one, with the company's name, address, tax ID and branch, showing 100 baht and 7 baht VAT separately
Printing from a till needs approval first
To print abbreviated tax invoices from a cash register or POS, the shop must apply for approval on form PP.06 at the Area Revenue Office where it is located, one application per business location, and may only use it once approved. Using it before approval carries a penalty under section 90/3 of up to 6 months in prison, a fine of up to 10,000 baht, or both.
Tax invoices and copies must be kept at the shop for at least 5 years from the date of issue
What you can do in GORINY
For a shop set as VAT-registered, a counter sale with no customer selected is issued automatically as an abbreviated tax invoice. The slip and A4 copy are headed abbreviated tax invoice with a note that prices include VAT. If the customer wants a full invoice, select them in the customer field on the sales screen before taking payment and that bill becomes a full tax invoice.
The program does not file PP.06 for you. The shop files it, then enters the machine number it receives under POS terminals, and slips print that number. A bill already issued cannot change type afterwards; issue a credit note and a new bill. The output tax report sums abbreviated tax invoices per day; confirm this approach with your accountant.
For the items a full tax invoice must show, read the article on what a correct tax invoice must include
Free tools for this topic
Use them right away, no sign-up
Frequently asked questions
- Can input tax be claimed from an abbreviated tax invoice?
- No. VAT on an abbreviated tax invoice is non-claimable input tax. A VAT-registered buyer who wants to claim it must ask the shop for a full tax invoice.
- Can a shop refuse a customer's request for a full tax invoice?
- No. The Revenue Department handbook says a retailer must issue a full invoice with a copy every time the buyer asks.
- Can an abbreviated tax invoice be in English?
- Yes. The Revenue Department handbook allows Thai or English, in baht, with Thai or Arabic numerals. Other languages need approval first.
Sources
Checked against official announcements on 19 November 2026
Related features
Get new articles and ask about store tax on LINE
Add GORINY's LINE OA as a friend. We only send things your store can actually use.
Get articles like this by email
1 to 2 emails a month, unsubscribe anytime
Try it with your own store's data
Sign up yourself right away for a free 14-day trial, then you decide whether to continue. Or try the sample shop first.