Articles | Updated 15 November 2026
Delivery note, billing note and receipt: what is the difference and when does a wholesaler issue each one
A delivery note is issued when goods are delivered, a billing note when you ask for payment, and a receipt when the money arrives. A wholesaler that sells on credit uses all three. This article walks through one full month at a drinking-water wholesaler.


How the three documents differ
A billing acknowledgement is the slip the customer signs and returns to the seller, confirming the bill was received and the agreed payment date. Some shops have the customer sign the copy of the billing note instead.
Delivery note
When it is issued: Every delivery
What it shows: What was delivered, how many, and who received it
Tax point of view: VAT-registered sellers often combine it into one delivery note/tax invoice
Billing note or invoice
When it is issued: When you ask for payment, for example at month end
What it shows: Amount due, the delivery notes it covers, and the payment date
Tax point of view: A business document, not a receipt
Receipt
When it is issued: When payment is received
What it shows: How much was received, from whom, and when
Tax point of view: The person receiving the money must issue a receipt under section 105
| Document | When it is issued | What it shows | Tax point of view |
|---|---|---|---|
| Delivery note | Every delivery | What was delivered, how many, and who received it | VAT-registered sellers often combine it into one delivery note/tax invoice |
| Billing note or invoice | When you ask for payment, for example at month end | Amount due, the delivery notes it covers, and the payment date | A business document, not a receipt |
| Receipt | When payment is received | How much was received, from whom, and when | The person receiving the money must issue a receipt under section 105 |
Example: a drinking-water wholesaler delivers to a corner shop 4 times a month
A VAT-registered drinking-water wholesaler delivers 12-bottle packs to a corner shop by the market every Tuesday, at 48 baht a pack before VAT. They agree to bill at month end, with payment due within 15 days of billing. All figures are examples.
3 Nov 2026
Quantity: 50 packs
Before VAT (baht): 2,400.00
VAT 7% (baht): 168.00
Total (baht): 2,568.00
10 Nov 2026
Quantity: 40 packs
Before VAT (baht): 1,920.00
VAT 7% (baht): 134.40
Total (baht): 2,054.40
17 Nov 2026
Quantity: 60 packs
Before VAT (baht): 2,880.00
VAT 7% (baht): 201.60
Total (baht): 3,081.60
24 Nov 2026
Quantity: 50 packs
Before VAT (baht): 2,400.00
VAT 7% (baht): 168.00
Total (baht): 2,568.00
Month total
Quantity: 200 packs
Before VAT (baht): 9,600.00
VAT 7% (baht): 672.00
Total (baht): 10,272.00
| Delivery date | Quantity | Before VAT (baht) | VAT 7% (baht) | Total (baht) |
|---|---|---|---|---|
| 3 Nov 2026 | 50 packs | 2,400.00 | 168.00 | 2,568.00 |
| 10 Nov 2026 | 40 packs | 1,920.00 | 134.40 | 2,054.40 |
| 17 Nov 2026 | 60 packs | 2,880.00 | 201.60 | 3,081.60 |
| 24 Nov 2026 | 50 packs | 2,400.00 | 168.00 | 2,568.00 |
| Month total | 200 packs | 9,600.00 | 672.00 | 10,272.00 |
Step by step: which document, and who keeps which copy
- Step 1: on delivery day the driver brings a delivery note/tax invoice with the water. The corner shop checks the quantity and signs. The original stays with the corner shop and the signed copy goes back to the wholesaler, so by month end there are 4 of them.
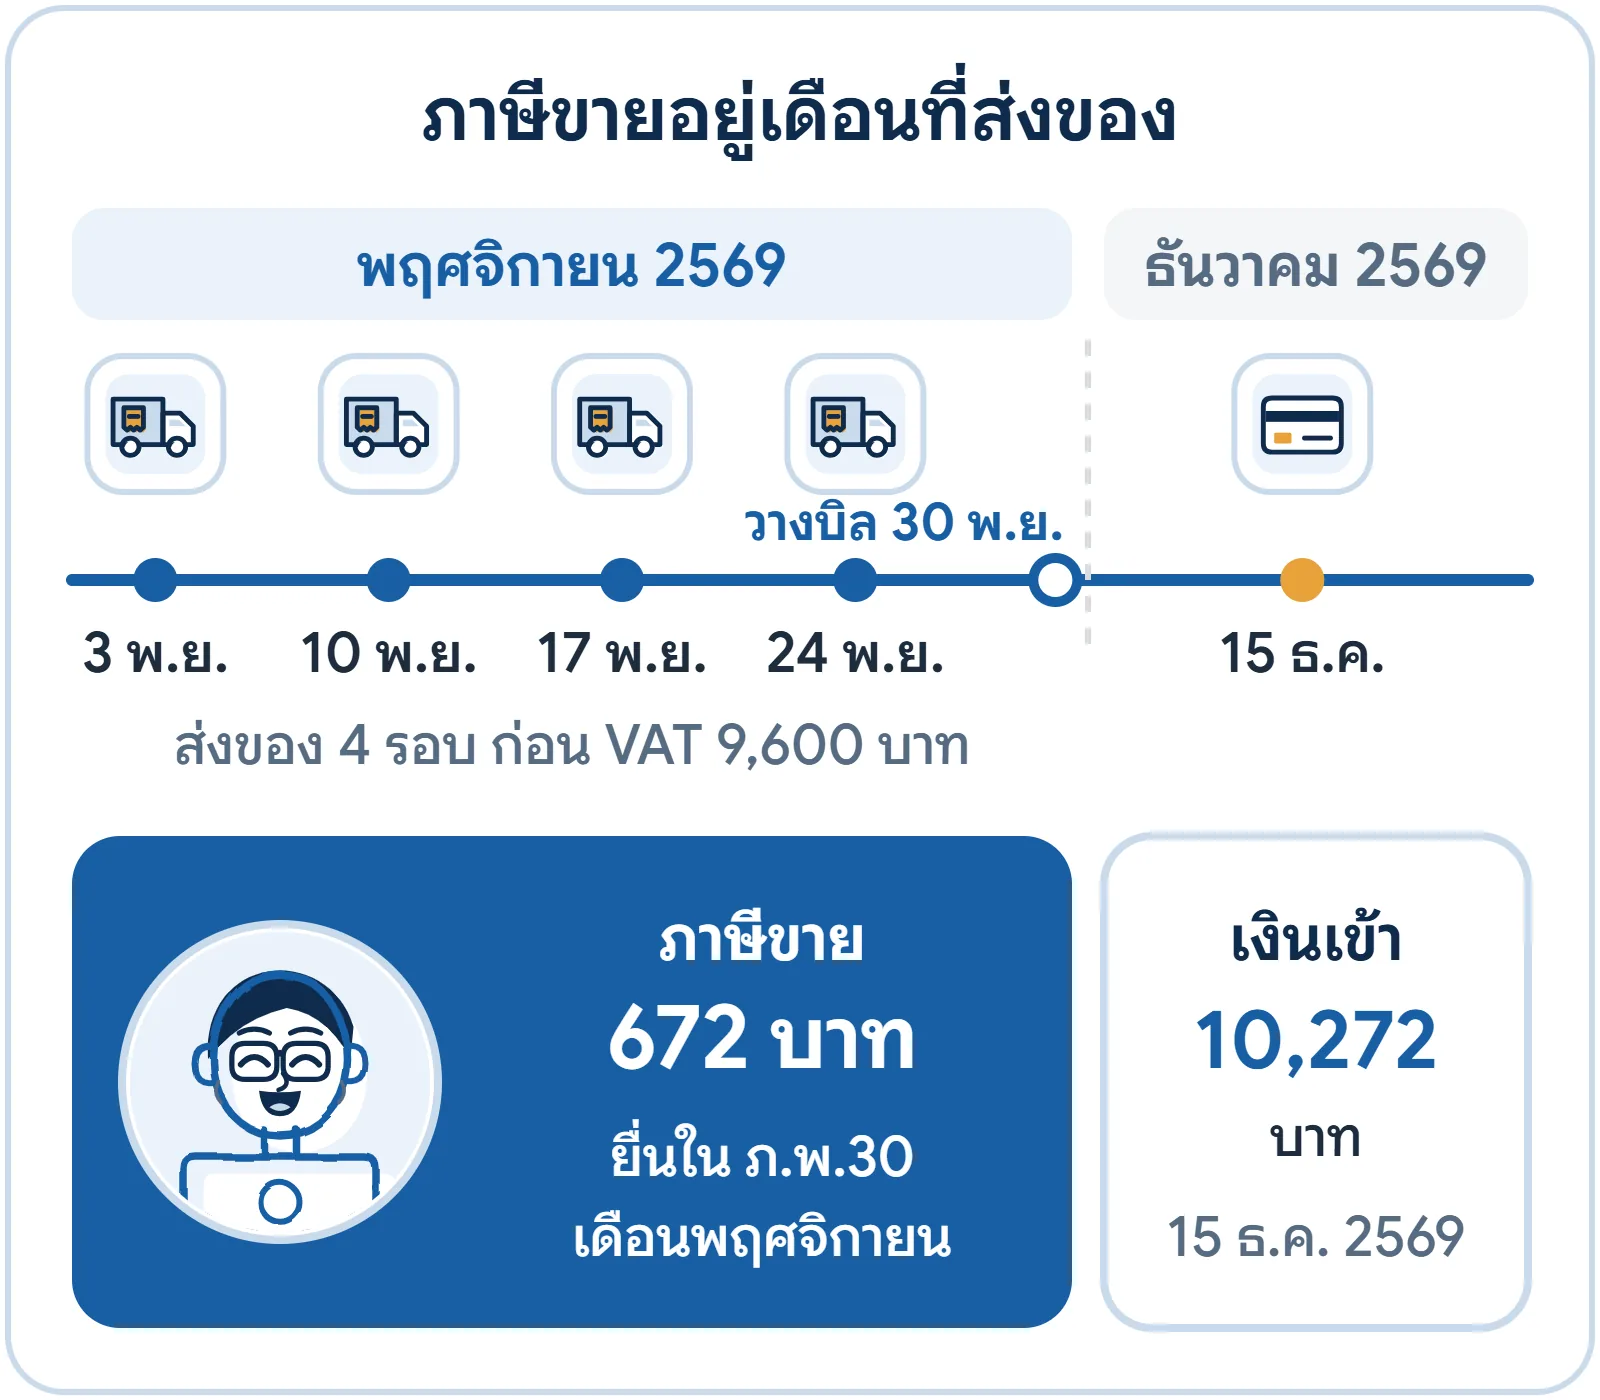
- Step 2: on 30 Nov 2026 the wholesaler issues one billing note listing all 4 delivery note numbers, total 10,272 baht, due 15 Dec 2026. The original goes to the corner shop, which signs a billing acknowledgement and returns it for the wholesaler to keep.
- Step 3: on 15 Dec 2026 the corner shop transfers 10,272 baht. The wholesaler issues a receipt that refers to all 4 delivery note numbers. The original goes to the corner shop and the copy stays with the wholesaler.
Output VAT arises at delivery, not at billing
Revenue Code section 78 (1) says VAT on a sale of goods arises when the goods are delivered, unless ownership is transferred, payment is received or a tax invoice is issued before delivery. The Revenue Department tax invoice guide says to issue the tax invoice as soon as goods are delivered, and allows it to be combined with other business documents such as a delivery note, invoice or receipt. That is why VAT-registered wholesalers commonly use a delivery note/tax invoice.
In this example the 672 baht of output VAT from all 4 deliveries belongs to November and goes into the November PP.30, even though the money arrives in December. The billing note creates no new tax, and the receipt at payment does not need to be another tax invoice.
A seller paid on delivery can use a single receipt/tax invoice, because section 105 lets a tax invoice that shows the payment count as the receipt. Copies of tax invoices and receipts must be kept for at least 5 years.
A seller that is not VAT-registered may not issue tax invoices under section 86/13, so it uses a plain delivery note, billing note and receipt. Everything else stays the same. For your own shop's tax filing, check with your accountant.
Common mistakes
- Issuing the tax invoice with the month-end bill when the goods went out early in the month, so the tax invoice comes later than the tax point.
- Delivering at the end of one month, billing early the next, and reporting the output VAT in the billing month, which is the wrong month.
- A billing note that does not list the delivery note numbers, so the customer cannot check the amount and pays late.
How GORINY helps wholesalers with this
Take one order and deliver in rounds. On the B2B wholesale page, create a sales order, then record each delivery with the quantity actually sent. Every round gets a delivery note number and stock is reduced by what was sent.
Invoices are dated on the delivery date for you. Press Bill on a delivery round and the program prices it as quantity delivered times the sales order price, adding VAT according to your business settings. The invoice is dated on the delivery date, not the day you pressed the button, so output VAT lands in the delivery month. For a VAT-registered business with the buyer's name on file, it prints as an invoice/tax invoice. Each delivery note can be billed only once, so nothing is charged twice.
Know at month end exactly what to collect. The customer statement shows that customer's unpaid invoices, the total and how long each has been outstanding. When the customer transfers the money, press Receive payment on that invoice and the balance goes down by itself.
The B2B wholesale page is part of the Business plan.
Free tools for this topic
Use them right away, no sign-up
Frequently asked questions
- Are a billing note and an invoice the same thing?
- In everyday trade they are used interchangeably. Both tell the customer how much to pay and when. Some sellers issue an invoice for every delivery and then gather them into one billing note at month end.
- Can a delivery note be used as a receipt?
- No. A delivery note shows the goods were delivered, not that you were paid. When you receive the money, issue a receipt.
Sources
Checked against official announcements on 15 November 2026
Related features
Get new articles and ask about store tax on LINE
Add GORINY's LINE OA as a friend. We only send things your store can actually use.
Get articles like this by email
1 to 2 emails a month, unsubscribe anytime
Try it with your own store's data
Sign up yourself right away for a free 14-day trial, then you decide whether to continue. Or try the sample shop first.